Sezzle: Buy Now, Pay Later

- 14.79K Reviews
- 4.5
- Downloads
- 5,000,000+
Our take on Sezzle: Buy Now, Pay Later from Appgk
When a shopping app is used on a shared household device, the real question is not only whether it helps you pay. It is also whether everyone can tell whose purchase is being arranged, which payment schedule belongs to whom, and what happens when several people use the same phone. I found Sezzle: Buy Now, Pay Later most useful when treated as a personal shopping and payment tool rather than a family wallet. It can divide an eligible purchase into four or five interest-free payments, let you pay over time, and provide rewards, but the person using it still needs to stay closely involved in every order.
That distinction matters because the app sits between ordinary shopping and short-term credit-style budgeting. It is free to download, aimed at Everyone, and belongs to the Shopping category. Sezzle Mobile develops it, and its strong store presence—an average rating of 4.5 from roughly 113 thousand ratings and more than 5 million installs—suggests that many shoppers find the basic idea convenient. My experience is that the convenience is real, but it works best when I already know exactly what I am buying and how each future payment will fit into my budget.
How Sezzle fits into a shared household
A realistic example is a household shopping for school supplies, clothing, or a replacement kitchen item. One person finds the product, another person may be responsible for the budget, and a third person might use the shared phone to check an order. Sezzle can make the initial purchase feel more manageable by spreading it across scheduled payments, yet that does not automatically make the purchase a shared responsibility. The account holder should remain the person who understands the order and expects the later charges.
I would avoid treating the app like a communal shopping list. If several people browse on one device, it is easy to lose track of which checkout belongs to which person. A better routine is to decide the buyer before opening the payment flow, complete one purchase at a time, and review the resulting schedule immediately. That small pause is more valuable than it sounds. It prevents a household from confusing a planned purchase with a completed one or assuming that another person has agreed to cover a later installment.
Best Parts of Sezzle: Buy Now, Pay Later
Things to Keep in Mind About Sezzle: Buy Now, Pay Later
The app is especially practical for a shopper who wants a clear alternative to paying the full amount at once. It is less suitable when the household budget is already tight or when the buyer needs one simple total with no future payment dates to remember. Splitting a purchase can improve short-term cash flow, but it does not reduce the actual cost of the goods. I found that keeping the original full price visible while deciding helped me judge whether the purchase was genuinely affordable.
Rewards add another reason to keep shopping activity inside the app, but I would not let them drive a purchase. A reward is useful only after the product, delivery terms, and payment plan make sense. In a shared setting, this is an important boundary: a family member should not buy something merely because the app presents an attractive benefit. The household still needs to agree on the item and the person responsible for the payments.
News and Features Related to Sezzle: Buy Now, Pay Later

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Setting up clear boundaries before the first order
The safest setup is personal and deliberate. I would use the account for one shopper, keep the sign-in process private, and avoid handing the phone around while an order is being created. This is not because shared-device use is automatically a problem; it is because payment apps are easier to manage when the person making the purchase can see the complete process from product selection through confirmation.
Before checking out, I recommend confirming four things in plain language: the item being bought, the total amount, the installment arrangement, and who will monitor the later payments. This is a simple household agreement rather than an app feature, and it removes much of the confusion that can arise when one person shops and another person assumes responsibility afterward.
Don't want to read the full review?
Sezzle is free to download, which makes trying it straightforward, but “free” should not be confused with free shopping. The product still costs money, and the payment commitment continues after the excitement of checkout has passed. I would explain that distinction to anyone sharing the device, especially a younger user who may focus on the first payment rather than the full obligation.
The current version is 5.3.5, and the app supports Android 7.0 or later. That makes it accessible on many older Android phones, which is helpful in households where the shared device is not new. Still, compatibility is only one part of a smooth setup. The phone should have enough battery and a stable connection during checkout, and the buyer should have time to read the payment details rather than rushing through them while someone else is waiting to use the device.
Screenshots
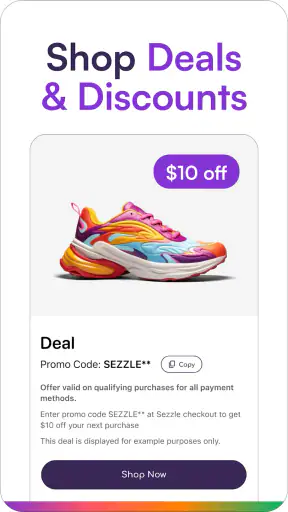
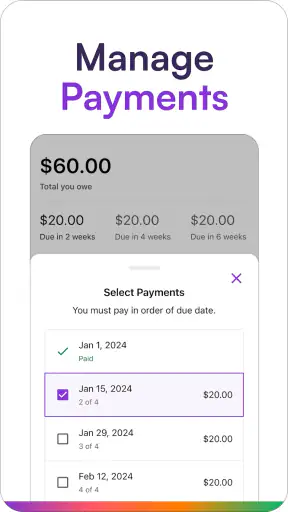
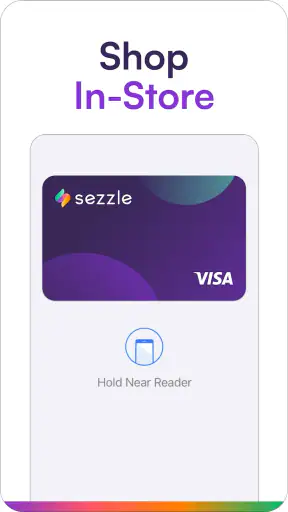
One useful habit is to separate browsing from buying. A household member can look at products first, discuss the choice, and only then open the payment portion once the decision is final. This reduces accidental orders and makes it easier to compare Sezzle with paying directly by card, using a bank transfer, or waiting until the full amount is available. The app is most helpful as a considered payment option, not as a reason to skip the decision-making stage.
Coordinating orders without creating household confusion
Coordination becomes more important when multiple purchases are made close together. I would keep a simple household note with the item, buyer, purchase date, and upcoming payment dates. It does not need to contain sensitive account information. Its purpose is only to make responsibilities visible, particularly when one person pays and another person uses the item.
This approach also helps with returns or changes of mind. The person who placed the order should be the one to start checking what needs to happen next, rather than assuming that the person who requested the item will handle everything. Buy-now-pay-later arrangements can make a return feel less immediate because the household may already be thinking about the product rather than the payment schedule. Keeping the order and its owner together avoids that disconnect.
For a shared household, I see one non-obvious advantage in using the app carefully: it can create a natural checkpoint before a purchase. Instead of treating checkout as one large payment that disappears from view, the buyer has to think about how the purchase will be divided over time. That can encourage more deliberate budgeting. The trade-off is that the same structure can make several small purchases look harmless when their combined future payments are not harmless at all.
Because of that, I would not open separate payment plans for several impulse purchases simply because each individual installment looks small. If a family is shopping for several people, grouping decisions by need and reviewing the combined amount is wiser than evaluating each product in isolation. Sezzle can organize a payment, but it cannot replace household budgeting.
Compared with paying directly with a debit card, the main difference is timing. A debit card gives the household one immediate deduction and a simpler record, while Sezzle spreads the payment and may offer rewards. Direct payment is usually easier for someone who wants no continuing schedule. Compared with a credit card, Sezzle may feel more focused because the purchase is divided into a defined arrangement rather than blended into a revolving balance, but a credit card may be more familiar for people who already track it carefully. The better option depends on whether the household values staged payments or simplicity.
Age, trust, and who should be in charge
The Everyone content rating describes the app’s general audience, not a blanket recommendation for every child to manage purchases independently. In my view, the account and payment decisions should stay with an adult or with the person who is genuinely responsible for the money. A younger household member may help choose an item, but that does not mean they should control the checkout or be expected to understand every future payment without guidance.
This is where trust matters more than convenience. A shared phone can make an account appear available to anyone who picks it up, even though the financial responsibility belongs to one person. I would explain clearly that browsing is not permission to buy, and that entering a payment flow is different from adding something to a wish list. If a teenager is involved, I would have them show the full purchase to the responsible adult before confirmation.
I also would not assume that the app itself will solve household boundaries. The practical protection comes from the family’s routine: private account access, a named buyer, and a quick review after checkout. Those steps are more dependable than relying on everyone to remember which screen they last saw. If the household cannot agree on who may use the account, Sezzle is probably not the right tool for that shared device.
Another point worth considering is emotional pressure. A person may feel comfortable asking for a product when the first payment appears smaller, while the person managing the household budget sees the full commitment differently. I think the responsible buyer should discuss the total before discussing the installment amount. That keeps the conversation focused on affordability rather than on how easy the first step looks.
When the app is a strong fit—and when I would skip it
I would recommend Sezzle to an organized shopper who wants to spread an eligible purchase into four or five interest-free payments, can monitor the schedule, and appreciates having shopping and rewards connected in one place. It can be a sensible option for a planned purchase when the full amount is already accounted for in the household budget and the installments simply match the timing of incoming money.
I would skip it for someone who frequently forgets bills, makes several small purchases without recording them, or prefers the certainty of paying once and being finished. I would also choose a direct payment method when a household is sharing one device but cannot maintain clear account boundaries. In that situation, the convenience of a split payment is outweighed by the chance of misunderstandings.
The app is not a substitute for an emergency fund, and I would be cautious about using it for essentials when there is no realistic plan for the later payments. Spreading a necessary purchase may help with timing, but it can also postpone a problem. The strongest use case is a planned item that the buyer can afford overall, not a purchase that is affordable only if everything goes perfectly afterward.
Its audience size gives me some confidence that the central shopping flow is approachable, and the 4.5 average rating is encouraging. However, a rating cannot tell me whether the app suits a particular household’s habits. A high level of adoption does not remove the need to read each checkout carefully, especially when several people share a device or when the buyer is comparing payment methods.
My household verdict after using it
My final impression is that Sezzle is most valuable when it adds structure to a purchase that has already been decided. The ability to divide an order into interest-free payments can make timing easier, and the rewards angle gives regular shoppers another reason to return. The app is free, widely used, and available to people running Android 7.0 or later, so it is not difficult to fit into an ordinary shopping routine.
For household use, though, I would keep the arrangement personal. One named account holder should make the purchase, understand the schedule, and coordinate with anyone else who benefits from the item. A shared phone can work, but only when the family treats the app as a personal financial tool rather than a common wallet. That single rule prevents most of the confusion I would worry about.
My practical recommendation is to decide the total budget first, then use Sezzle only if the payment schedule improves timing without hiding the real cost. If you can track the installments and maintain clear boundaries, it is a useful alternative to paying everything immediately. If you want the simplest possible household accounting, paying directly is likely better. For me, that makes Sezzle: Buy Now, Pay Later a convenient option for disciplined shoppers, but not an automatic solution for shared-device spending.
Sezzle Mobile has built an app that makes staged shopping easy to understand at a glance, yet the responsibility still belongs to the person behind the order. Used thoughtfully, it can support planned purchases and rewards without becoming confusing. Used casually across a household, it can make responsibility less clear. I would recommend it to an organized adult shopper, with the strongest advice being simple: keep the account boundaries visible, discuss the full price, and never let the smaller first payment make the decision for you.
Sezzle: Buy Now, Pay Later FAQ
What is Sezzle: Buy Now, Pay Later, and how does it work?
Sezzle is a buy now, pay later service that lets eligible shoppers split a purchase into several scheduled payments instead of paying the full amount immediately. After selecting Sezzle at a participating retailer, you generally make an initial payment and the remaining installments are charged automatically according to the displayed schedule. Approval, payment amounts, and available plans can vary by user, retailer, and transaction.
Does using Sezzle affect my credit score?
Sezzle may use different types of credit checks depending on the product, account, and payment option you choose. Some applications may involve a soft check that does not affect your credit score, while certain longer-term or credit-building features could involve credit reporting or additional checks. Before confirming an order, review the specific terms shown in the app and understand whether late payments may be reported.
Are there fees or interest charges when using Sezzle?
Many standard Sezzle installment purchases may be available without interest when payments are made on time, but fees can still apply in particular situations. Possible costs may include late fees, payment rescheduling fees, service charges, or interest associated with specific financing products. The exact cost depends on your account, location, retailer, and selected plan, so always check the payment summary before completing checkout.
What happens if I miss a Sezzle payment or need to change my payment date?
If a scheduled payment cannot be processed, Sezzle may retry the charge, restrict new purchases, or apply a fee depending on the applicable terms. The app may offer payment-date changes or other management tools, although eligibility and charges can vary. It is best to update your payment method promptly, review notifications, and contact Sezzle support rather than ignoring a failed installment.
Can I use Sezzle for every online or in-store purchase, and what are the requirements?
Sezzle is not accepted everywhere, so you must shop with participating merchants or use an available in-app shopping option. Eligibility can depend on your age, location, identity verification, payment method, account history, purchase amount, and automated approval decision. Even if you have used Sezzle before, a new transaction may be declined or offered different payment terms based on current account and order details.